Car Accident Settlement Timeline: How Long Does It Take?
Car accident settlement timeline how long does it take? Get realistic stages and timelines, plus a free case review at (833)-248-4565 to protect your claim.
By Fatima Rahimi
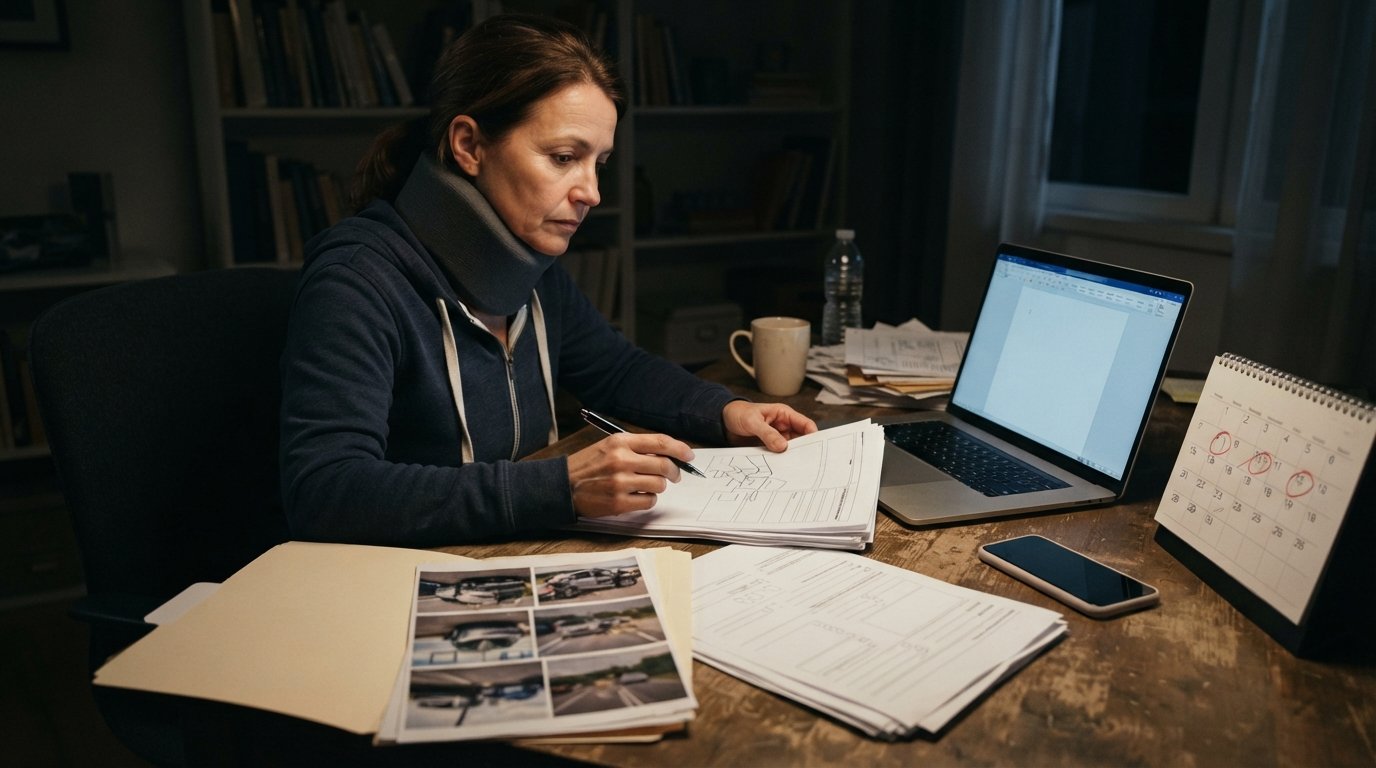
After a car crash, the paperwork and medical appointments can feel endless, and the question on almost every injured person's mind is simple: how long until this is over? The answer is rarely a single number, because a car accident settlement timeline depends on medical recovery, liability disputes, insurance company behavior, and whether a lawsuit becomes necessary. Some claims resolve in a few weeks, while others stretch past a year or more. Understanding the stages, the common delays, and the moments that change the clock can help you plan financially and make better decisions about your case.
The Typical Stages of a Car Accident Settlement
Most car accident claims follow a predictable arc, even if the speed varies. The process usually begins with the crash itself, followed by medical treatment, investigation, a demand package, negotiation, and finally a release and payment. Each stage has its own timeline, and skipping or rushing a stage often creates problems later.
Immediately after the crash, the priority is safety and medical care. Insurance companies are notified, a claim number is opened, and the at-fault driver's insurer may contact you quickly. Early contact is normal, but recorded statements and quick settlement offers at this stage deserve caution. The first few weeks are also when evidence is freshest: photos, witness names, police reports, and vehicle damage estimates should be gathered before memories fade or vehicles are repaired.
Once treatment is underway, the case moves into the investigation and documentation phase. Your attorney or you (if handling the claim yourself) will collect medical records, bills, wage loss documentation, and evidence of pain and inconvenience. This phase can take weeks to months, and it overlaps with treatment. A demand letter is typically not sent until treatment is complete or a doctor has declared you at maximum medical improvement, because the demand must reflect the full scope of injuries.
After the demand letter is sent, the insurance adjuster reviews it and responds, often with a counteroffer. Negotiation may involve several rounds of offers and counteroffers, and it can take anywhere from a few weeks to several months. If agreement is reached, a release is signed and payment usually arrives within a few weeks, though liens and medical bills must be resolved along the way. If negotiation fails, filing a lawsuit becomes the next step, which adds months or longer to the overall timeline.
Why Medical Treatment Length Drives the Timeline
No factor shapes a car accident settlement timeline more than the length of medical treatment. Insurers and attorneys both want to know the final diagnosis, the prognosis, and the total cost of care before valuing a claim. If you are still seeing doctors, a responsible demand cannot be finalized, because new treatment could change the value significantly.
Soft tissue injuries such as whiplash may resolve in a few weeks or months, allowing a claim to move forward relatively quickly. Fractures, surgeries, traumatic brain injuries, and spinal injuries often require months of treatment and rehabilitation, and some require future medical care. In those cases, the settlement timeline stretches to match recovery. A common mistake is settling too early, before the full extent of an injury is known, which can leave you responsible for medical bills that exceed the settlement.
Maximum medical improvement (MMI) is the point at which further treatment is unlikely to improve your condition. Attorneys often wait for MMI before sending a demand, because it provides a stable basis for valuation. If you are close to MMI, the timeline may be shorter; if you are facing surgery or ongoing therapy, expect the process to take longer. This is not delay for its own sake. It is a way to protect the value of your claim.
What Causes Delays in a Car Accident Settlement
Even a straightforward claim can hit delays. The most common culprits are liability disputes, insurance negotiation tactics, and medical liens. Knowing them in advance helps you recognize when a delay is normal and when it signals a problem.
Liability disputes arise when the other driver, or the insurer, denies fault or argues you share responsibility. Comparative fault rules in many states reduce recovery by your percentage of fault, and insurers use those rules to pressure claimants. Disputes over who ran a red light, whether speed contributed, or whether a lane change was safe can require additional investigation, witness statements, and sometimes accident reconstruction. Each step adds time.
Insurance negotiation is another source of delay. Adjusters may respond slowly, request additional documentation, or make low initial offers to test your resolve. Some delays are legitimate backlog issues, but others are strategic. A well-documented demand and organized records reduce the room for stalling. If negotiations stall completely, filing a lawsuit can change the dynamics, though it also adds time.
Medical liens and bills can complicate the end of a case. Hospitals, health insurers, and Medicaid or Medicare may assert liens on a settlement. These must be identified and resolved before funds are distributed, and disputes over lien amounts can delay payment even after a settlement is agreed. An attorney typically handles lien negotiations, which is one reason having representation can make the closing stages smoother. If you are exploring affordable legal help, a free case review through GoFreeLegal can connect you with participating attorneys without upfront cost.
How Long Does It Take? Realistic Ranges by Case Type
While every case is unique, general ranges help set expectations. The following estimates assume a car accident claim with clear liability and completed medical treatment. Cases with disputes, surgery, or litigation can take significantly longer.
- Minor injury, clear liability: Several weeks to about three months, especially if treatment is short and the insurer cooperates.
- Moderate injury with ongoing treatment: Three to nine months, driven largely by treatment length and negotiation rounds.
- Serious injury or disputed liability: Nine months to a year or more, often requiring expert review and extended negotiation.
- Lawsuit filed: One to three years or longer depending on court schedules, discovery, and trial dates.
These ranges are not promises. A claim that seems simple can slow down if the insurer requests records repeatedly or if a lien appears late. Conversely, a claim can move faster when documentation is complete and the adjuster has authority to settle. The key is to avoid artificial deadlines and to focus on building a complete record, because a rushed settlement often undervalues the claim.
When Filing a Lawsuit Becomes Necessary
Filing a lawsuit is not a sign that negotiations failed completely. It is often a tool to preserve rights and compel progress. The statute of limitations sets a deadline for filing, and once that deadline passes, the claim may be barred regardless of merit. State deadlines vary, and some are as short as one or two years, so waiting too long is risky.
Attorneys typically file suit when liability is disputed, when the insurer refuses to make a reasonable offer, or when the statute of limitations is approaching and negotiations are not progressing. Filing does not end settlement talks; many cases settle after a lawsuit is filed and discovery begins. The difference is that the court process imposes deadlines and can increase pressure on the insurer to negotiate seriously.
If you are handling a claim without an attorney, understanding the filing deadline in your state is essential. A missed deadline can end the claim entirely. For injured people seeking a no-cost, confidential review, services such as CheapInjuryLawyer.com can help match you with participating personal injury attorneys, many of whom work on contingency, so you can explore options without upfront cost. Neither the site nor any matching service can guarantee a settlement amount or outcome, but a review can clarify deadlines and next steps.
Practical Steps to Keep Your Settlement on Track
You cannot control the insurer, but you can control your side of the process. The following steps help prevent unnecessary delays and protect the value of your claim.
- Get medical care immediately and follow recommendations. Gaps in treatment are used by insurers to argue injuries are minor or unrelated.
- Document everything. Keep photos, witness information, police reports, medical records, and receipts for expenses.
- Do not post about the crash on social media. Insurers review public posts and may use them to dispute your claims.
- Avoid recorded statements and quick offers before treatment is complete. Early offers often do not reflect the full extent of injuries.
- Track deadlines, including the statute of limitations. Missing a deadline can end your claim regardless of fault.
These steps do not guarantee speed, but they reduce the chance that a delay is caused by missing records or inconsistent information. In many cases, the timeline is driven by factors outside your control, but a well-organized claim moves more smoothly through each stage.
What to Expect During Negotiation and Payment
Negotiation is often the longest phase after treatment ends. The demand letter sets out liability, injuries, damages, and a settlement figure. The adjuster may respond with a counteroffer, and the process repeats until both sides agree or the case moves to litigation. Each round can take days or weeks depending on the adjuster's workload and the complexity of the claim.
Once a settlement is agreed, you will sign a release. The release is a contract that ends the claim in exchange for payment, so it should be reviewed carefully. After signing, the insurer issues payment, often within a few weeks. If liens exist, they are paid from the settlement, and the remaining funds are distributed to you. This final stage can be delayed by lien negotiations, so it is wise to ask about liens early.
If you are represented, your attorney handles the demand, negotiation, and lien resolution, which can shorten the timeline by avoiding back-and-forth errors. If you are not represented, you can still negotiate, but expect to manage records and deadlines yourself. A free case review can help you decide whether representation makes sense for your situation.
In the end, the car accident settlement timeline is best understood as a range shaped by medical recovery and the behavior of insurers. Rushing often costs money; waiting too long can cost rights. The most reliable approach is to complete treatment, document thoroughly, and watch the statute of limitations. With that foundation, you can move through the process with clearer expectations and fewer surprises.